FIRC (Foreign Inward Remittance Certificate) is one of the most important documents in the export payment process for Indian businesses. Issued as proof that foreign currency has been received from an overseas buyer, it helps exporters demonstrate regulatory compliance, claim export incentives, and maintain a clear record of international transactions.
This guide explains what FIRC is, how to obtain it, how it differs from FIRA, and why it matters for every exporter collecting payments from abroad.
This guide explains what FIRC is, how to obtain it, how it differs from FIRA, and why it matters for every exporter collecting payments from abroad.
TL;DR
- FIRC (Foreign Inward Remittance Certificate) is a bank-issued document that proves your business received foreign currency from abroad, most often as payment for exported goods or services.
- Exporters use it to prove repatriation of export earnings, stay compliant with regulations, and claim certain export incentives. It pairs with the Bank Realisation Certificate (BRC), which shows the conversion into rupees.
- FIRC is not the same as FIRA (Foreign Inward Remittance Advice). Knowing which one you have, and which a scheme or authority requires, matters at claim time.
What is FIRC?
Priya exports handloom textiles from Kerala to buyers in Europe. A payment lands in her account in euros, the deal closes, and months later an incentive scheme asks her to prove that money actually came from abroad. The document that settles the question is her FIRC.
For an exporter, it is proof of payment received against exported goods or services: it confirms you were paid in foreign currency and that the international transaction genuinely completed.
That evidentiary role is why FIRC sits at the centre of so much export paperwork. It is the record that ties a foreign payment in your account to a specific export, which is exactly what regulators, banks, and incentive schemes want to see.
What is FIRC used for?
A FIRC (Foreign Inward Remittance Certificate) is a document issued by an Indian bank confirming that money has been received in India from abroad. It records the sender’s details, the amount in foreign currency, the INR amount credited, the exchange rate, and the purpose of the payment. For exporters, freelancers, and businesses receiving international payments, it serves as official proof that the money came from outside India for a legitimate reason.
Here are its main uses.
Proving export of services for GST. Services provided to overseas clients are treated as zero-rated exports under GST, but only if payment is received in convertible foreign currency. The FIRC is the key proof of this, so it’s needed when exporting under a Letter of Undertaking (LUT) or when claiming a GST refund on exported services.
Income tax records. A FIRC helps show the source and nature of foreign income when filing your income tax return, and it’s useful supporting evidence if the tax department ever asks you to explain a large foreign credit in your bank account.
FEMA and RBI compliance. Every foreign inward remittance must be reported under the correct purpose code. The FIRC documents this, helping you show that export proceeds were realised within the permitted time and that the transaction complies with foreign exchange rules.
Foreign investment. When an Indian company receives foreign direct investment, the FIRC (along with the KYC report from the remitter’s bank) is needed to file Form FC-GPR with the RBI, which confirms the shares issued to the foreign investor.
Export incentives and audits. FIRCs support claims under government export schemes, help auditors verify foreign receipts, and are often requested by banks when you apply for export finance or other credit facilities.
Many banks now issue a FIRA (Foreign Inward Remittance Advice) or a digital e-FIRC instead of a physical certificate, and payment providers like PayPal and Payoneer offer downloadable equivalents. These generally serve the same purpose, though it’s worth confirming with your CA which document your GST refund or audit requires.
How to obtain FIRC for your export payments
You obtain a FIRC from the bank or authorised dealer that received your foreign payment. The bank issues it once it has verified and confirmed the remittance.
The process runs like this:
- Submit the supporting trade documents to your bank, typically the shipping bill, bill of lading, export invoice, and other transaction-related paperwork.
- The bank verifies the documents and confirms the foreign currency payment against them.
- On confirmation, the bank issues the FIRC as a concrete record of the transaction.
That certificate then becomes the document you rely on to meet various regulatory requirements tied to the payment. Where you collect through a modern cross-border payment provider rather than a traditional bank, the equivalent remittance proof (a FIRA, covered below) is often generated automatically on settlement, which removes the manual back-and-forth.
Purpose Codes on Your FIRC or FIRA
Every foreign payment received in India must be tagged with an RBI purpose code, a short alphanumeric code that tells the bank and the regulator why the money was sent. The code is printed on your FIRC or FIRA, and it decides how the payment is treated for foreign exchange reporting, GST, and income tax. Choosing the wrong one is one of the most common reasons exporters run into trouble at claim time.
Why the Purpose Code Matters
The purpose code is what classifies a payment as an export receipt rather than, say, a personal gift or a loan. If a freelancer’s payment for design work is tagged as a family remittance, for example, it no longer counts as export of services on paper, which can block a zero-rated GST claim or a GST refund. Banks also use the code to report the transaction to the RBI, so an incorrect code can create mismatches with your EDPMS records, invoices, and tax filings.
Common Purpose Codes for Exporters and Freelancers
| Purpose code | Description | Typically used by |
|---|---|---|
| P0102 | Realisation of export bills for goods | Exporters of physical goods |
| P0103 | Advance receipts against export contracts | Exporters receiving payment before shipment |
| P0802 | Software consultancy and implementation | IT services firms, developers |
| P0807 | Off-site software exports | Software companies delivering projects remotely |
| P1006 | Business and management consultancy and public relations services | Consultants, marketers, agencies |
| P1301 | Remittance by non-residents towards family maintenance and savings | Personal transfers, not export income |
| P1302 | Personal gifts and donations | Personal transfers, not export income |
How to Get the Purpose Code Right
Pick the code that most closely matches the service or goods you actually invoiced for, and keep it consistent across your invoice, FIRC or FIRA, and GST filings. Platforms like PayPal and Payoneer ask you to select a code when you withdraw, while banks may ask at the time the payment is credited. If you notice a wrong code after the payment has been credited, contact your bank as soon as possible to request a correction, since the change becomes harder to make once the transaction has been reported and the reporting period has closed.
Benefits of FIRC and its link to the BRC
A valid FIRC does real work for an exporter. It demonstrates the repatriation of foreign exchange earned through exports, which is essential for regulatory compliance and for claiming certain export incentives and benefits.
It also works as a pair with the Bank Realisation Certificate (BRC). The two documents show different halves of the same transaction:
- FIRC evidences the inflow of foreign currency into your account.
- BRC evidences the realisation of that foreign currency, its conversion into Indian rupees.
Together they give financial institutions, regulatory bodies, and government authorities a complete view of the payment, from foreign inflow through to rupee realisation. Many export incentive claims lean on this combined trail, which is why exporters keep both rather than treating either as optional.
FIRC vs FIRA: what is the difference?
FIRC and FIRA are related but not interchangeable, and confusing them causes real friction at claim time.
- FIRC (Foreign Inward Remittance Certificate) is a formal certificate, traditionally issued by banks as authoritative proof of a foreign currency inflow.
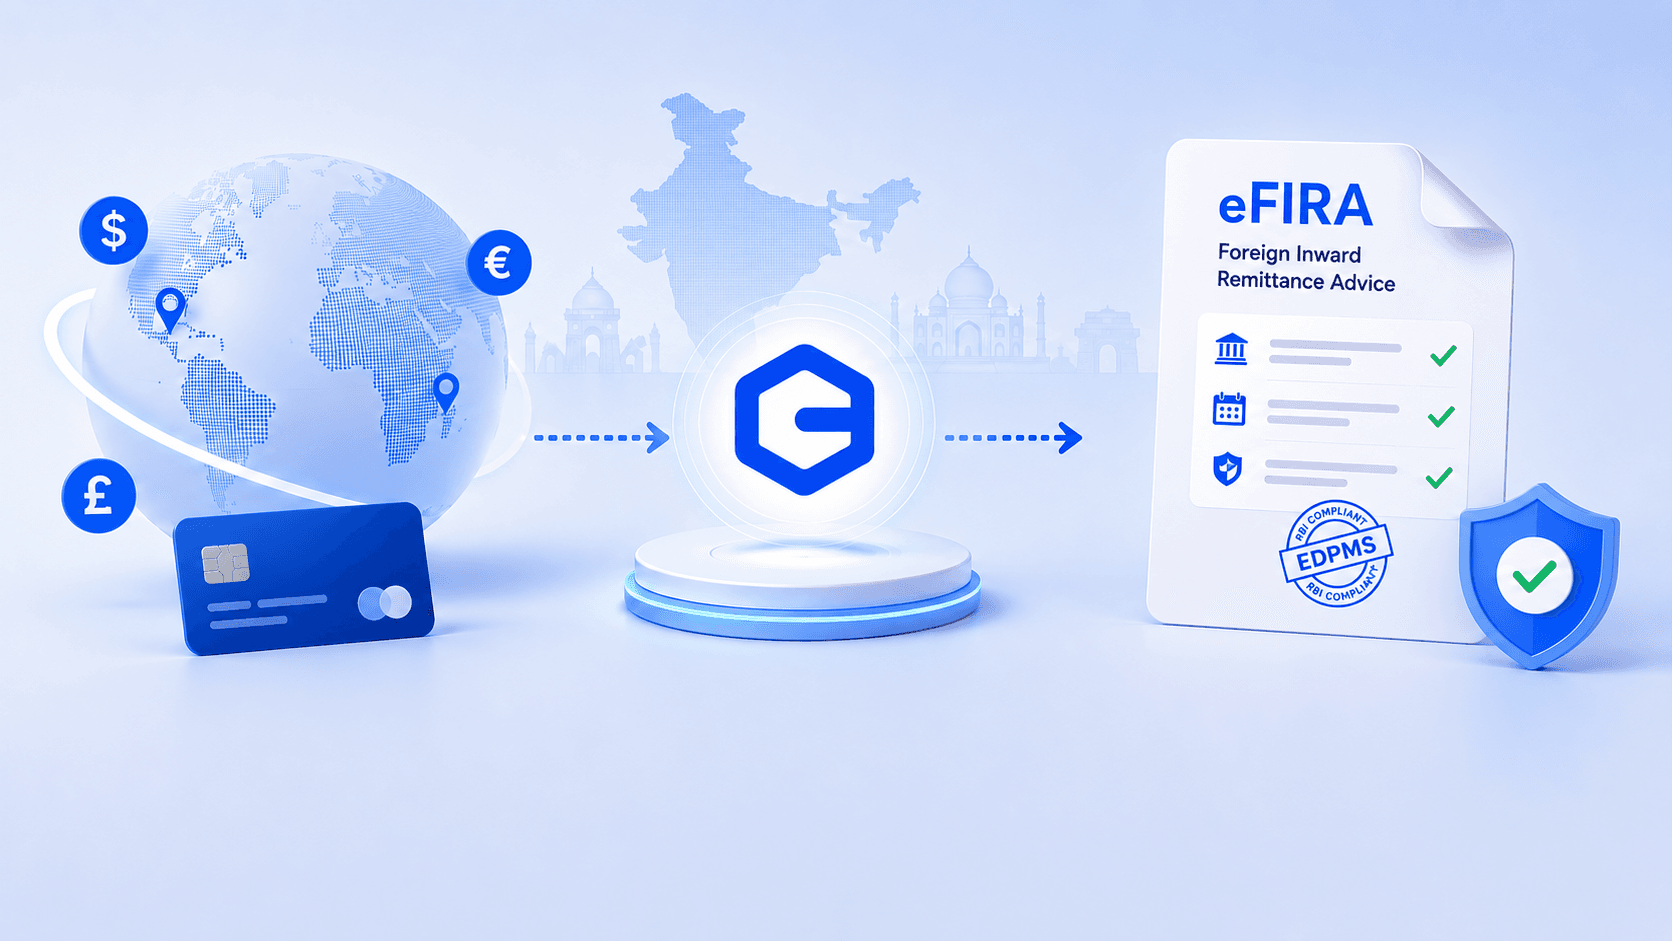
- FIRA (Foreign Inward Remittance Advice) is an advice document confirming the same inward remittance, commonly issued by payment providers and authorised dealers, often digitally as an e-FIRA.
In practice, most inward-payment proof issued by modern cross-border payment providers takes the form of a FIRA or e-FIRA, generated automatically once a payment settles. For many purposes a FIRA serves as accepted proof of inward remittance, but some schemes or authorities specify a bank-issued FIRC. The practical rule: check which document your specific scheme, buyer, or authority requires before you file, so you request the right one up front.
e-FIRC and e-FIRA: Digital Certificates
As cross-border payments have moved online, most banks and payment providers have replaced paper certificates with digital versions. An e-FIRC (electronic Foreign Inward Remittance Certificate) and an e-FIRA (electronic Foreign Inward Remittance Advice) serve the same purpose as their paper counterparts, confirming that money was received in India from abroad, but they’re issued digitally, can be downloaded instantly, and are usually digitally signed by the issuing bank.
What Is an e-FIRC?
An e-FIRC is the digital form of the traditional FIRC. It’s a formal certificate issued by your bank, usually on request, confirming the details of one or more inward remittances: the sender, the amount in foreign currency, the INR value credited, the exchange rate, and the purpose code. Because it’s digitally signed, it’s generally accepted as proof of foreign receipts for GST, income tax, and audit purposes without needing a stamped paper copy.
What Is an e-FIRA?
An e-FIRA is a transaction-level advice that confirms a single foreign payment was credited to your account. Many banks and payment providers generate it automatically for every inward remittance, so you don’t need to request it separately. It carries the same core details as an e-FIRC and is widely used as proof of export realisation, especially by freelancers and businesses receiving frequent international payments.
e-FIRC vs e-FIRA
| Aspect | e-FIRC | e-FIRA |
|---|---|---|
| Full form | Electronic Foreign Inward Remittance Certificate | Electronic Foreign Inward Remittance Advice |
| Nature | Formal certificate | Transaction advice |
| How it's issued | Usually on request from your bank | Often generated automatically for each payment |
| Coverage | One or more remittances | A single remittance |
| Cost | Some banks charge a fee | Usually free |
| Common use | GST refunds, audits, FDI reporting | Proof of payment, GST and tax records, export realisation |
How to Get Your e-FIRC or e-FIRA
For bank transfers, you can usually download them from your bank’s internet banking under the foreign remittance or trade section, or request them from your branch or relationship manager. If you’re paid through a cross-border payment provider such as PayPal, Payoneer, or PayGlocal, the advice is typically available in your account dashboard for each settled payment. Make sure the purpose code and payer details are correct when you download it, since errors are much harder to fix later during a GST refund or audit.
Why Digital Certificates Matter
Digital certificates remove the delays of collecting paper documents from a branch, make record-keeping easier, and reduce the risk of losing proof of a payment months after it arrived. For exporters filing GST refunds or reconciling export proceeds in EDPMS, having a digital trail for every transaction also makes it far simpler to match payments with invoices and shipping bills.
Essential details in a FIRC
A complete FIRC should carry the details that let anyone reading it tie the payment to the export unambiguously:
- The exporter's name and address.
- The beneficiary's name, where the payment involves a third party.
- The amount received in foreign currency.
- The purpose of the payment (export of goods or services).
- The date the payment was received.
- The currency exchange rate applied for conversion into Indian rupees.
Accurate, complete information here is not a formality. A discrepancy between the FIRC and your other trade documents can stall an incentive claim or a compliance check later, so it is worth verifying every field when the certificate is issued rather than when a claim is already in motion.
How to Get a FIRA for Every International Payment with PayGlocal
Chasing your bank for a FIRA after every international payment takes time, and missing one can hold up a GST refund or an audit months later. With PayGlocal, a FIRA is generated for each international payment you receive, so your proof of export is ready as soon as the money lands in your account.
Getting started takes just a few steps:
- Sign up and complete your KYC. Create your PayGlocal account and submit your business details, PAN, and bank account information for verification.
- Collect payments from overseas clients. Share an invoice or payment link with your client, who can pay using their preferred international payment method.
- Receive funds in your Indian bank account. The payment is settled in INR to your linked account, tagged with the right purpose code for your business.
- Download your FIRA from the dashboard. Each settled payment comes with its FIRA, ready to download and use for GST, income tax, and compliance records.
No more branch visits, no manual requests, and no gaps in your paperwork at claim time.
Start receiving international payments with PayGlocal →