From the QR code at your neighbourhood café to the one displayed at online checkout, paying by scanning has become a familiar part of everyday shopping. Instead of handling cash or typing account details, customers can scan a code, review the payment and approve it on their phone.
But what happens between scanning a QR code and a successful payment? And should businesses use the same QR code for every customer or generate a new one for each transaction? This guide explains how QR code payments work, the difference between static and dynamic QR codes, their advantages and limitations, and how businesses can start accepting them.
But what happens between scanning a QR code and a successful payment? And should businesses use the same QR code for every customer or generate a new one for each transaction? This guide explains how QR code payments work, the difference between static and dynamic QR codes, their advantages and limitations, and how businesses can start accepting them.
TL;DR
- QR code payments let customers scan a code to open payment details in a supported banking or payment app and authorise the transaction.
- Static QR codes usually keep the same payment destination, while dynamic payment QR codes can include the amount and transaction reference for a particular purchase.
- QR payments can reduce manual data entry and make checkout convenient, but businesses still need to verify successful payment and watch for fraud.
- In India, UPI QR payments are common. PayGlocal supports UPI Dynamic QR Code as one of its UPI checkout options.
What are QR code payments?
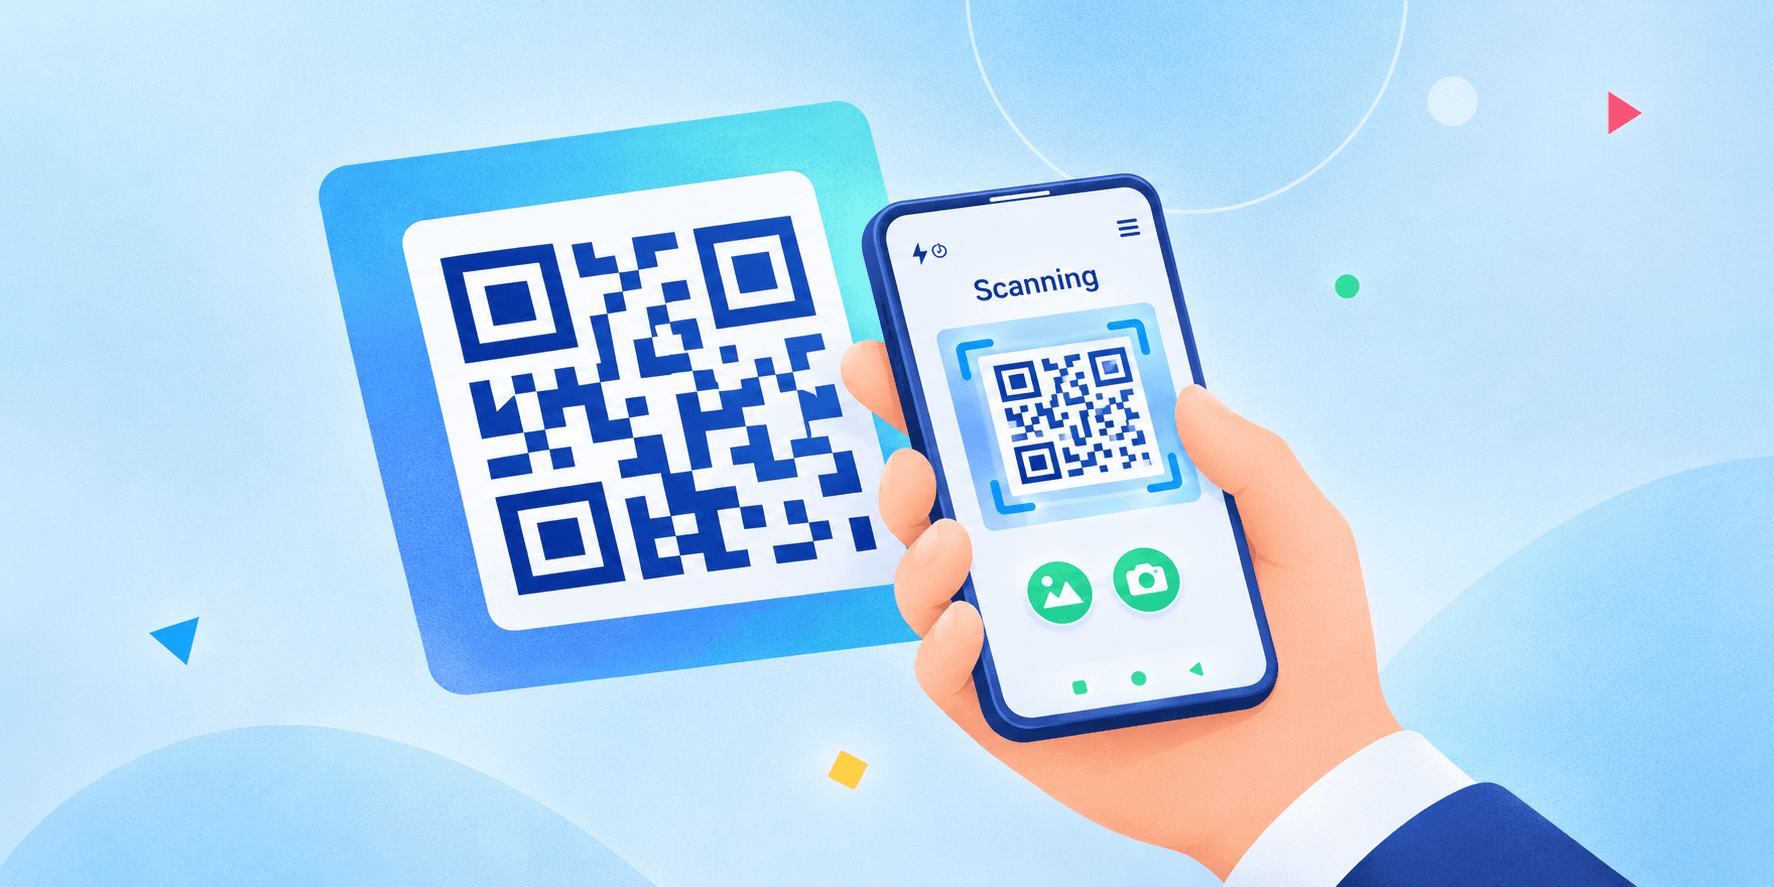
QR code payments are digital transactions initiated by scanning a Quick Response (QR) code. A QR code is a two-dimensional barcode that stores information in a pattern of small squares. When scanned with a compatible app, it can direct the customer to payment details or a secure checkout page.
For a UPI QR code payment in India, the code typically includes the recipient's UPI payment information. Depending on how the code was generated, it may also include the amount and a transaction reference. The customer checks the details and authorises the payment through their UPI app.
A QR code is not a payment method on its own. It is a convenient way to pass payment information to an app or checkout that actually processes the transaction.
How do QR code payments work?
Although the experience takes only a few taps, several steps happen in the background.
- The business displays a QR code. It may be printed at the counter, shown on a billing screen or added to an invoice or checkout page.
- The customer scans the code. A supported payment app or phone camera reads the encoded details and opens the relevant payment flow.
- The app displays the payment details. The customer can see the recipient and, for some codes, a pre-filled amount and transaction reference.
- The customer reviews and authorises the payment. For a typical UPI payment, this involves confirming the transaction in the UPI app and entering the UPI PIN or using another supported authentication method.
- The payment is processed. The banking and payment systems communicate the transaction result to the customer and merchant, subject to their provider's setup.
- The merchant checks the payment status. The business confirms that the payment was successful before handing over goods or treating an invoice as paid.
For example, a customer buying a ₹350 lunch might scan the café's UPI QR code, enter ₹350 if the amount is not already filled in, verify the café's name and approve the payment. The café should check its own payment notification or transaction record, not rely only on the customer's screenshot.
What are the different types of QR codes used for payments?
Two types are especially important for merchants: static QR codes and dynamic payment QR codes.
Static QR code
A static payment QR code usually displays the same recipient details each time it is scanned. A shop can print it once and place it near the cash counter for repeated use.
With a typical static UPI QR code, customers enter the amount themselves. This makes the code simple to reuse, but it also means customers can enter an incorrect amount. If the code does not include an invoice reference, matching payments to individual orders may require extra checks.
Static payment QR codes are often useful for small shops, kiosks, donation counters and businesses that want a simple scan-and-pay option.
Dynamic QR code
A dynamic payment QR code is generated for a particular transaction or payment request. It can carry the correct amount, merchant information and reference details, reducing the need for customers to type anything beyond authorisation.
For instance, a restaurant's billing system can generate a QR code for a ₹1,260 bill. The customer scans it and sees the payment amount already filled in. The transaction reference can also help the restaurant match the payment to that bill.
Dynamic payment QR codes are useful for businesses processing many orders, accepting different amounts or needing easier transaction reconciliation. The term *dynamic QR* is also used for changeable website-link QR codes; those are not necessarily payment QR codes.
Static vs dynamic QR code: which should businesses choose?
If customers pay different amounts at a physical counter and simple setup matters most, a static QR code may be sufficient. If the business needs the amount to be pre-filled, a reference linked to the order or smoother reconciliation, a dynamic payment QR code is usually the better fit.
The right choice depends on the payment provider's capabilities, transaction volume and how the business tracks orders.
Where are QR code payments used?
QR code payments are useful in more places than physical shop counters.
Retail shops and local businesses
Stores, salons, clinics and service providers can display a QR code for customers who prefer to pay using a smartphone. This can reduce reliance on cash and separate card-payment hardware.
Restaurants and cafés
Businesses can print a reusable code at the counter or generate a payment-specific QR code on the bill. Customers scan it and complete the payment without passing their card or cash to staff.
Online stores and checkout pages
An e-commerce website can display a payment QR code on a desktop checkout screen for the customer to scan with their phone. On a mobile checkout, an app-to-app payment flow, such as UPI Intent, can be more convenient than asking someone to scan a code displayed on the same device.
Invoices and remote payments
A business can include a QR code in an invoice or payment request so customers can open the relevant payment flow. The actual payment options depend on the provider and the customer's supported apps.
Events, donations and temporary counters
Event organisers and charities can display payment QR codes at stalls, on printed materials or on screens to make one-time contributions and purchases easier.
What are the benefits of QR code payments for businesses?
QR payments can simplify collecting money, particularly where customers are comfortable paying by phone.
- Convenient checkout: Customers can scan and confirm rather than enter the recipient's payment details manually.
- Lower hardware requirements: A printed QR code can be enough to initiate supported payments, although businesses still need a suitable merchant payment setup.
- Fewer entry errors: Pre-filled merchant details, and amounts in dynamic codes, can reduce typing mistakes.
- Flexible use: Codes can be displayed at a counter, in a bill, on a website or alongside an invoice.
- Easier reconciliation with dynamic codes: Transaction references can help businesses connect successful payments to particular orders.
- Contactless experience: Customers can pay using their own devices without exchanging cash or physically handing over a card.
These benefits are not automatic. Payment confirmations, settlement timing, provider charges and reporting features vary by payment method and service provider.
How can a business start accepting QR code payments?
The exact setup varies by provider, but most businesses follow a similar process.
1. Choose a payment provider
Select a bank or payment service provider that supports the QR payment method you need. Check whether it offers static QR codes, transaction-specific dynamic QR codes, reporting and refunds.
2. Complete merchant onboarding
Provide the business and banking details requested by the provider. The documents and verification checks depend on the payment product and merchant category.
3. Generate the QR code
For a static code, the provider generally creates a reusable payment QR linked to the merchant. For a dynamic code, a supported checkout or billing system generates the code for a particular order or amount.
4. Test the payment experience
Before using it with customers, confirm that the code opens the correct payment flow, displays the intended merchant details and produces a visible transaction status in the merchant's records.
5. Display the code and monitor payments
Use the code at checkout or on invoices, then track successful, pending and failed transactions through your provider's app or dashboard. Keep the merchant's displayed QR code protected from physical tampering.
Are QR code payments safe?
QR code payments can be secure when customers use trusted apps, verify the recipient and follow the payment method's authentication steps. However, a QR code is simply a way to encode information; it does not independently guarantee that the destination is genuine.
Fraudsters may replace a merchant's printed QR code, share misleading payment requests or encourage customers to scan a code under the false claim that it is necessary to receive money.
To reduce risk, customers and businesses should follow a few basic checks:
- Verify the recipient's name and payment amount in the app before authorising a transaction.
- Do not enter a UPI PIN to receive money. NPCI warns that scanning a QR code and entering a UPI PIN is for making payments, not receiving them.
- Inspect printed codes regularly for stickers or signs of replacement.
- Use trusted apps and payment pages rather than unfamiliar links sent by unknown contacts.
- Verify the merchant-side transaction status before marking a sale as paid. A screenshot alone is not proof of successful receipt.
- Raise payment issues through the provider or bank if a transfer appears pending, failed or misdirected.
These precautions matter just as much for QR codes shared digitally as they do for codes displayed in physical stores.
What are the limitations of QR code payments?
QR code payments are convenient, but they are not the right solution for every transaction.
- App and device compatibility: The customer needs a supported device, payment app and available payment method.
- Connectivity issues: Completing an online payment generally depends on network and payment-system availability.
- Manual amount errors: Customers using some static QR codes may enter the wrong amount.
- Reconciliation challenges: Reusable codes without an order reference may make it harder to match payments to invoices.
- QR code fraud: Tampered codes and deceptive payment requests can redirect customers or trick them into authorising payments.
- Different geographic coverage: A domestic UPI QR code does not automatically support payments from every international customer or payment app.
A business selling both in India and internationally may therefore need more than one payment acceptance method.
How does PayGlocal support QR and digital payments?
PayGlocal supports UPI Dynamic QR Code as one of its UPI checkout options, alongside UPI Intent and UPI Collect, subject to the merchant's enabled payment setup. A dynamic QR code can give customers a simple scan-to-pay option for supported INR transactions.
For businesses selling to overseas customers, PayGlocal also offers an International Payment Gateway with international card payments and alternative payment methods. International checkout should be configured for the countries and payment options a merchant actually serves; an Indian UPI QR code should not be treated as a universal cross-border payment method.
Choosing the right combination of QR, UPI, cards and other methods helps businesses give customers payment choices that match how they prefer to pay.
Key takeaways
QR code payments make it easier for customers to initiate transactions by scanning rather than entering payment information manually. Static codes provide a reusable option, while dynamic payment QR codes can connect a particular payment to a bill or order.
For businesses, the best setup is one that combines convenient checkout with accurate payment confirmation and reconciliation. Whether you accept payments online or at a physical counter, checking the destination, amount and transaction status remains essential.