COMPARE

PayGlocal vs Skydo: What's better for Indian merchants in 2026?

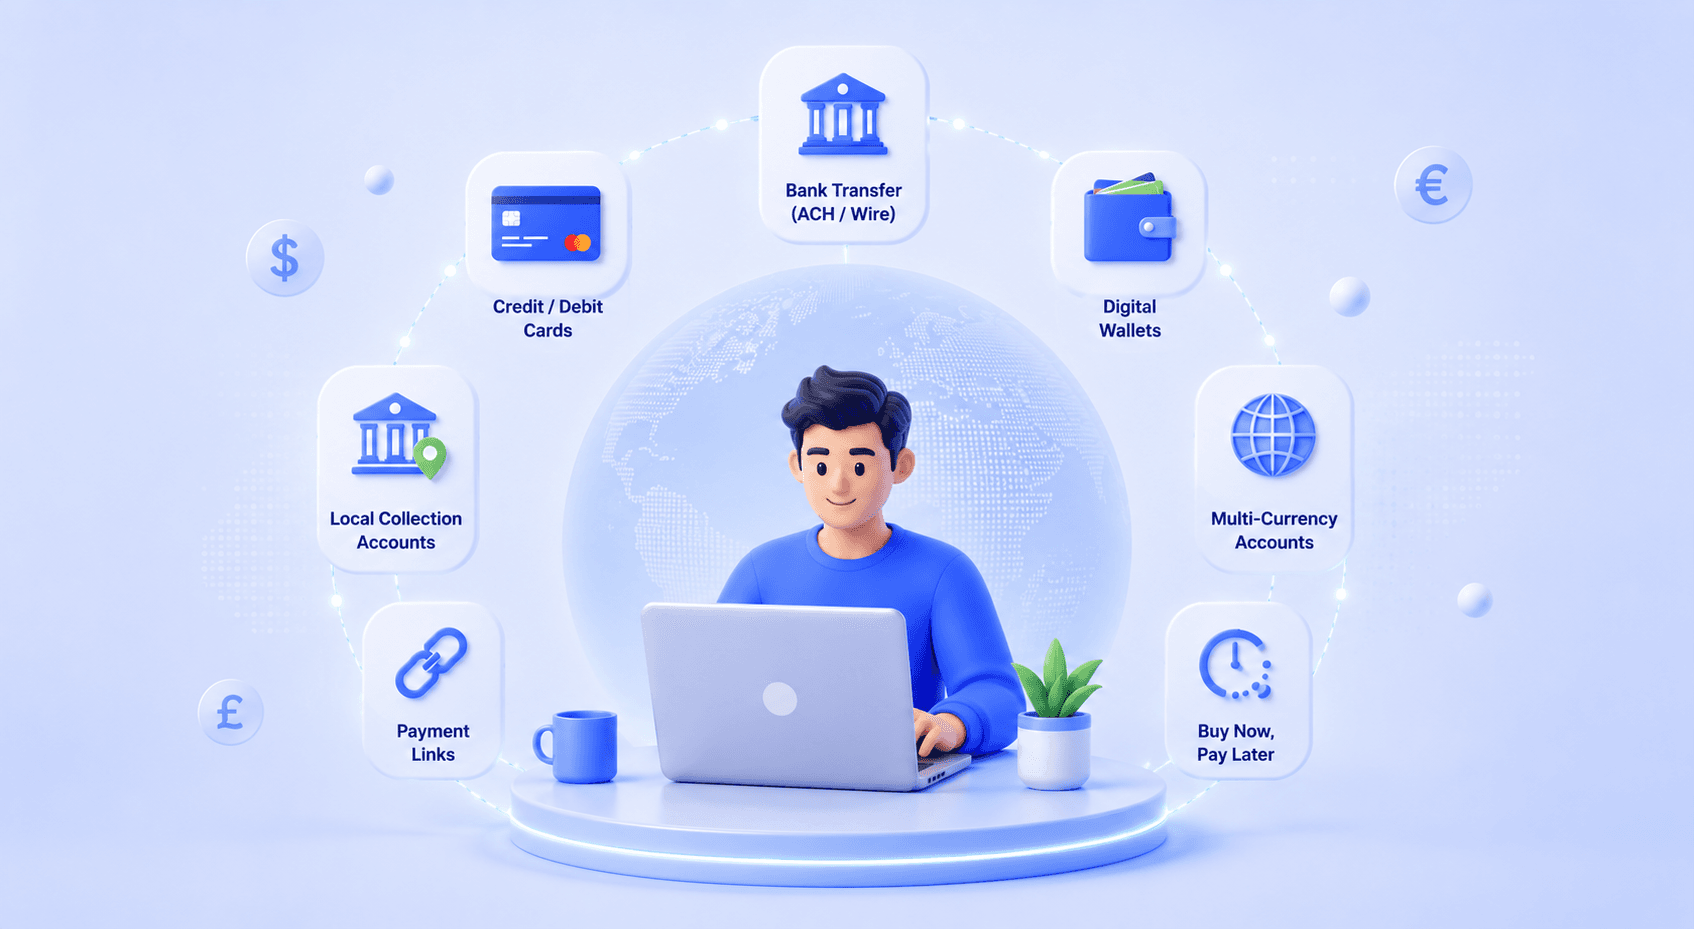
Skydo collects invoices over bank transfer. PayGlocal runs the full international revenue stack: card checkout, subscriptions, local payment methods and multi-currency collections, on RBI authorisations that cover inward & outward cross border and domestic payments.

See pricing
Your client pays
£
5002K10K50K100K
Fetching live rate…£1 GBP = ₹0.00 INR
PayGlocalBest rate
—
 
Conversion rate
1 GBP = ₹0.00
Fee
£0.00
You receive
₹0.00
skydo
—
 
Conversion rate
1 GBP = ₹0.00
Fee
£0.00
You receive
₹0.00
Calculating your savings…

Rates are indicative. Final amount may vary.

Takes less than 5 minutes to activate
RBI PA-CB Inward and OutwardRBI PA-O8,000+ Indian businessesUp to 96% payment success rateLowest multi-currency account pricingRBI PA-CB Inward and OutwardRBI PA-O8,000+ Indian businessesUp to 96% payment success rateLowest multi-currency account pricing
PayGlocal and Skydo, compared
Short answer

It depends on the size and requirements of your business.

If your money only arrives as a handful of large invoices paid through bank transfer and no other channel, Skydo can be an equally good fit.

If your money arrives as card payments at a checkout, renews every month, or lands in many small invoices, a large fee starts working against you and a receiving account cannot process the payment at all.

That is the ground PayGlocal is built for: authorisation, retries and routing that lift approval rates to as high as 96%, plus multi-currency accounts for the invoices you still collect by transfer.

PayGlocal vs skydo at a glance

PayGlocal
skydo
Built for
Businesses collecting internationally through checkout, subscriptions and invoices along with global currency accounts
Exporters and freelancers collecting invoices through global currency accounts
International card acceptance
Yes, hosted and embedded checkout, 2.75% published card rate
Recurring and standing instructions on international cards
Alternate payment methods, Apple Pay, wallets
Multi-currency accounts
Yes, 33+ currencies, zero FX markup, INR settlement in under 24 hours
Yes, virtual accounts in 10+ countries, zero FX markup
Pricing model
Up to 50% lower fees across tiers
Flat fee per transfer: $19, $29, or 0.3% above $10,000, plus GST
Payment success rate optimisation
Yes, dynamic routing, retries, tokenisation, 3DS handling
Not applicable, no authorisation layer
FIRA
Automated with every transaction
RBI authorisations
PA-CB Inward and Outward, plus PA-O for domestic
PA-CB Inward and Outward

Real cost breakdown

The cost question, answered honestly

Rhea runs a six-person design studio in Pune. Most of her invoices land between $800 and $1,800, and about a fifth of her clients pay by card because their procurement teams will not raise a SWIFT transfer for a small amount.

What matters is what it works out to on the invoice sizes you actually raise.

Skydo's published rate card

For payments up to
$2,000 USD
You pay$19
For payments of
$2,001 USD to $10,000 USD
You pay$29
For payments above
$10,000 USD
You pay0.3%
  • Add 18% GST to each
  • No markup on the exchange rate

The same rate card, expressed as a percentage

Invoice size
Fee incl. GST
Effective rate
$500
$22.42
4.48%
$1,000
$22.42
2.24%
$2,000
$22.42
1.12%
$2,001
$34.22
1.71%
$5,000
$34.22
0.68%
$25,000
$88.50
0.35%

What falls out of place?

A $22 fee is a large percentage in disguise on a $500 invoice.

You will need multiple partners for multiple payment methods, which is not scalable and adds a big operational overhead as you scale.

Flat fees, compared

Two flat-fee models, side by side

Skydo charges $19 up to $2,000, $29 from $2,001 to $10,000, and 0.3% above that, plus 18% GST. PayGlocal charges $10 up to $2,000, $18 from $2,000 to $7,500, and 0.25% above that, plus 18% GST.

Same structure. Roughly half the fee.

PayGlocal
skydo
Up to USD 2,000
Flat fee for smaller invoices
$10
$19
USD 2,000 to USD 7,500
Flat fee for the next tier
$18
$29
Above tier threshold
Percentage fee beyond that
0.25%
0.3%
GST
Applied on top of every fee
18%
18%

What that works out to per invoice

Invoice
PayGlocalincl. GST
skydoincl. GST
You keep
$500
$11.80 (2.36%)
$22.42 (4.48%)
$10.62
$1,000
$11.80 (1.18%)
$22.42 (2.24%)
$10.62
$2,000
$11.80 (0.59%)
$22.42 (1.12%)
$10.62
$5,000
$21.24 (0.42%)
$34.22 (0.68%)
$12.98
$10,000
$29.50 (0.30%)
$34.22 (0.34%)
$4.72
$25,000
$73.75 (0.30%)
$88.50 (0.35%)
$14.75

There is no invoice size at which the other rate card is cheaper. Not at $500, not at $25,000.

Send us your last three months of invoices and we will model both, line by line.

Honest fit check

We are not the only right answer for everyone

When Skydo is a good call

You can also pick Skydo if all of this is true.

  • Your invoices are consistently above $10,000
  • You are using HDFC account as your bank, and you accept SGD as local rails
  • Every client is happy to pay by bank transfer
  • You never need to take a card at checkout
  • Nothing you sell renews on a schedule
  • You do not need a domestic gateway or outward payments alongside your collections
Collecting an international invoice payment

Where PayGlocal wins

Pick PayGlocal if any of this sounds like you.

On a plain bank transfer into a multi-currency account, both platforms do the same thing: local collection rails, mid-market rate with no FX markup, INR settlement, FIRA attached. Nothing about the money movement differs. The fee does. Ours runs roughly 50% lower at every slab, and the rate card is the whole cost. No setup fee, no platform fee, no maintenance, no charge per FIRA.

A virtual account can accept a transfer. It cannot authorise a card, handle 3DS, retry a soft decline, or route a transaction through a different acquirer when the first one fails. Card payment links exist as a bolt-on, and they are priced accordingly. If cards are more than a rounding error in your revenue, that gap compounds every month.

Standing instructions on international cards are hard, and most cross-border collection tools do not support them. If you sell a subscription, a retainer or a SaaS plan to overseas customers, you need recurring on the rails themselves, not an invoice reminder.

The most expensive thing in cross-border payments is not the fee. It is the payment that never went through. One PayGlocal merchant moved from 75% to 95% approval on international cards. On $100,000 of monthly attempted volume, that is $20,000 a month that used to fail silently, which no fee comparison on any pricing page will show you.

PayGlocal holds RBI authorisation as a Payment Aggregator Cross Border for both Inward and Outward, and as an Online Payment Aggregator for domestic. One provider, one onboarding, one reconciliation, whether the money is coming in from a US buyer, going out to an overseas supplier, or moving between two Indian parties.

Full API, documentation at payglocal.in/docs, and India's first cross-border MCP server for agent-led commerce. If your roadmap has anything automated on it, you need a platform, not a dashboard.

Founder growing an international business with PayGlocal
50%
lower fees at every slab

Switching over

Moving across takes about 24 hours

1

Onboard

KYC and documentation, typically cleared in 24 hours.

2

Get set up

Get your collection details and checkout keys.

3

Go live

Update your invoice templates and your checkout integration.

You keep your clients, your invoice history and your compliance trail. Old FIRAs stay downloadable from wherever they were issued.

Bring us your numbers

Average invoice size, monthly volume, and the split between card and bank transfer. We will model both options against your actual revenue and tell you if the answer is not us.

Business owner reviewing their revenue
PayGlocalPricing model
Average invoice size
Monthly volume
Card vs bank transfer split
Your real cost, modeled

Frequently asked questions.

Yes, at every slab. PayGlocal charges $10 up to $2,000, $18 up to $7,500, then 0.25%. Skydo charges $19, $29 and 0.3%. Both add GST and neither adds an FX markup, so the fee is the only difference. Their fee also jumps at $2,000, so a $2,001 invoice costs $12 more than a $2,000 one.

If every payment is a bank transfer against an invoice, either works, and ours costs about half. If any money comes through a checkout, renews monthly, or moves inside India, only PayGlocal can handle it.

$10 up to $2,000, $18 up to $7,500, then 0.25%, plus GST. Cards are 2.75%. Nothing else: no setup fee, no platform fee, no maintenance fee, no charge for FIRA.

PA-CB for Inward and Outward, plus PA-O (Payment Aggregator - Online). Money into India, out of India, and within India, on one onboarding. Certificate of Authorisation No. 250/2025.

Yes. Checkout, wallets and Apple Pay at 2.75%. We also retry declined cards and route them to a second acquirer, which is what lifts approval rates.

About 24 hours or one business day. Onboarding clears in 24 hours, then update your invoices and checkout and you are good to proceed.

Your next international payment can land differently. Setup your PayGlocal Multi-Currency Account in 10 minutes.