A customer says they paid your invoice, but the money is not showing in your account.
The quickest way to investigate is usually not the amount or date. It is the payment reference ID attached to the transaction.
The important point is that “payment reference ID” is a broad term. Different payment systems use different identifiers, and one payment can carry several of them at once.
The quickest way to investigate is usually not the amount or date. It is the payment reference ID attached to the transaction.
The important point is that “payment reference ID” is a broad term. Different payment systems use different identifiers, and one payment can carry several of them at once.
TL;DR
- A payment reference ID is an identifier used by a bank, payment system, gateway, or merchant to track a transaction.
- Different rails use different references: UPI uses a 12-digit transaction reference/RRN, RTGS has a 22-character UTR, and SWIFT payments carry a 36-character UETR.
- A single card or bank payment can have more than one valid reference because different systems add their own identifiers.
- Keep the system-generated reference together with your invoice or order number to simplify reconciliation and payment investigations.
What is a payment reference ID?
A payment reference ID is a code associated with a transaction so the relevant bank, network, gateway, or merchant system can identify it later. There is no single universal format.
A better way to think about it is:
Your invoice/order reference → payment-provider reference → network/bank reference → settlement reference
All can relate to the same payment.
How does a payment reference ID work?
A typical transaction can move through several systems:
Payment initiated → identifier assigned → transaction processed → status changes → settlement → reconciliation
Each system may preserve the original reference or create another one, which is why support teams often ask for a specific identifier.
What payment reference numbers might you see?
| Payment type | Common identifier | What it is used for |
|---|---|---|
| UPI | 12-digit transaction reference/RRN | Identifies the UPI transaction |
| RTGS | 22-character UTR | Uniquely identifies an RTGS transaction |
| NEFT | Bank/transaction reference or UTR | Used by the bank to identify the transfer |
| SWIFT payment | 36-character UETR | End-to-end payment tracking |
| Card payment | Gateway/acquirer/network references | Authorisation, processing, refunds, reconciliation |
| Marketplace payout | Platform payout/reference ID | Links a seller payout to platform records |
The label shown to you can differ by bank, app, gateway, or marketplace.
What Is a UPI Reference ID (UPI Reference Number)?
A UPI reference ID, also called the UPI reference number or UTR/RRN, is a unique 12-digit number created for every UPI transaction.
You can find it in your UPI app's transaction details, and you can use it to track a payment, confirm it was received, or raise a complaint with your bank if a payment fails.
NPCI's standard for UPI account-statement narration includes a 12-digit transaction reference number, or RRN.
Some banking and payment apps may label this reference as a UTR, transaction ID, or reference number in the user interface.
Where to Find Your UPI Reference ID in GPay, PhonePe, Paytm and BHIM
| App | Where to Find It | Usually Labelled As |
|---|---|---|
| Google Pay (GPay) | Open the app → scroll down and tap See transaction history → tap the payment | UPI transaction ID |
| PhonePe | Tap the History tab → tap the payment | UTR |
| Paytm | Tap Balance & History → tap the payment | UPI Ref. No. |
| BHIM | Tap Transactions or History → tap the payment | UPI Ref. ID / RRN |
What is an RTGS UTR?
RBI defines the Unique Transaction Reference (UTR) for RTGS as a 22-character code used to uniquely identify an RTGS transaction.
Use it when the beneficiary has not received the transfer or the bank needs to investigate it. Do not assume every payment rail uses the same UTR format.
What is a SWIFT UETR?
For SWIFT payment instructions, the key end-to-end identifier is the Unique End-to-end Transaction Reference (UETR).
SWIFT defines it as a 36-character reference issued by the originating party and carried through the payment chain.
It lets banks trace the same payment across the correspondent chain. MT103 is a SWIFT payment message format, not the payment reference itself.
What references appear on card payments?
Card payments can have several identifiers.
A transaction may include a merchant reference, gateway transaction ID, authorisation code, network/acquirer reference, and settlement reference. The gateway ID may find the payment in your dashboard, while another reference may be needed for a deeper trace.
Where can you find a payment reference ID?
| Where to check | What you may find |
|---|---|
| Banking app | UTR, transaction ID, bank reference |
| UPI app | Transaction reference/RRN or UTR label |
| Payment receipt | Bank or gateway reference |
| Email/SMS confirmation | Transaction/reference ID |
| Bank statement | Narration and transaction reference |
| Payment gateway dashboard | Gateway transaction ID and merchant reference |
| SWIFT payment advice | UETR and bank references |
| Marketplace dashboard | Payout/reference ID |
Reference Number vs Transaction ID vs UTR
| Term | What It Is | Typical Format | Generated By | Best Used For |
|---|---|---|---|---|
| UPI Reference Number (RRN) | A unique number that identifies a UPI payment across the payer's bank, the payee's bank, and the UPI network | 12 digits | UPI network / banks | Tracking a UPI payment and confirming it with either bank |
| Transaction ID | An internal ID that the payment app or merchant assigns to the payment | Alphanumeric; length varies by app (for example, PhonePe IDs start with "T") | The UPI app or merchant | Raising a complaint with that specific app or merchant |
| UTR (Unique Transaction Reference) | A bank reference number for a fund transfer. For UPI payments, it is usually the same 12-digit number as the UPI reference number | 12 digits for UPI; longer for NEFT/RTGS (16 or 22 characters) | Banks | Bank-level tracking and reconciliation, especially for NEFT, RTGS, and IMPS |
Quick tip: For a UPI payment, share the 12-digit UPI reference number (UTR) with your bank. Share the transaction ID when you contact the app's support team.
Why do payment reference IDs matter?
References help with payment investigations, reconciliation, refunds, disputes, audit trails, and duplicate detection. They are especially useful when identical amounts, FX conversion, or settlement deductions make amount-only matching unreliable.
Merchant reference vs system-generated reference
A merchant reference is the ID you create for your order or invoice; a system-generated reference comes from the bank, network, or provider. Using both is useful:
Invoice 4821 → merchant reference → payment-provider ID → settlement
This keeps your internal books connected to the external payment trail.
How PayGlocal handles payment identifiers
PayGlocal documents two important identifiers:
- GID (PayGlocal ID): generated by PayGlocal when a transaction is initiated and used for tracking, reconciliation, refunds, and follow-on API activity.
- MUID (Merchant Unique ID): generated by the merchant so the PayGlocal transaction can be linked back to the merchant's own order or record.
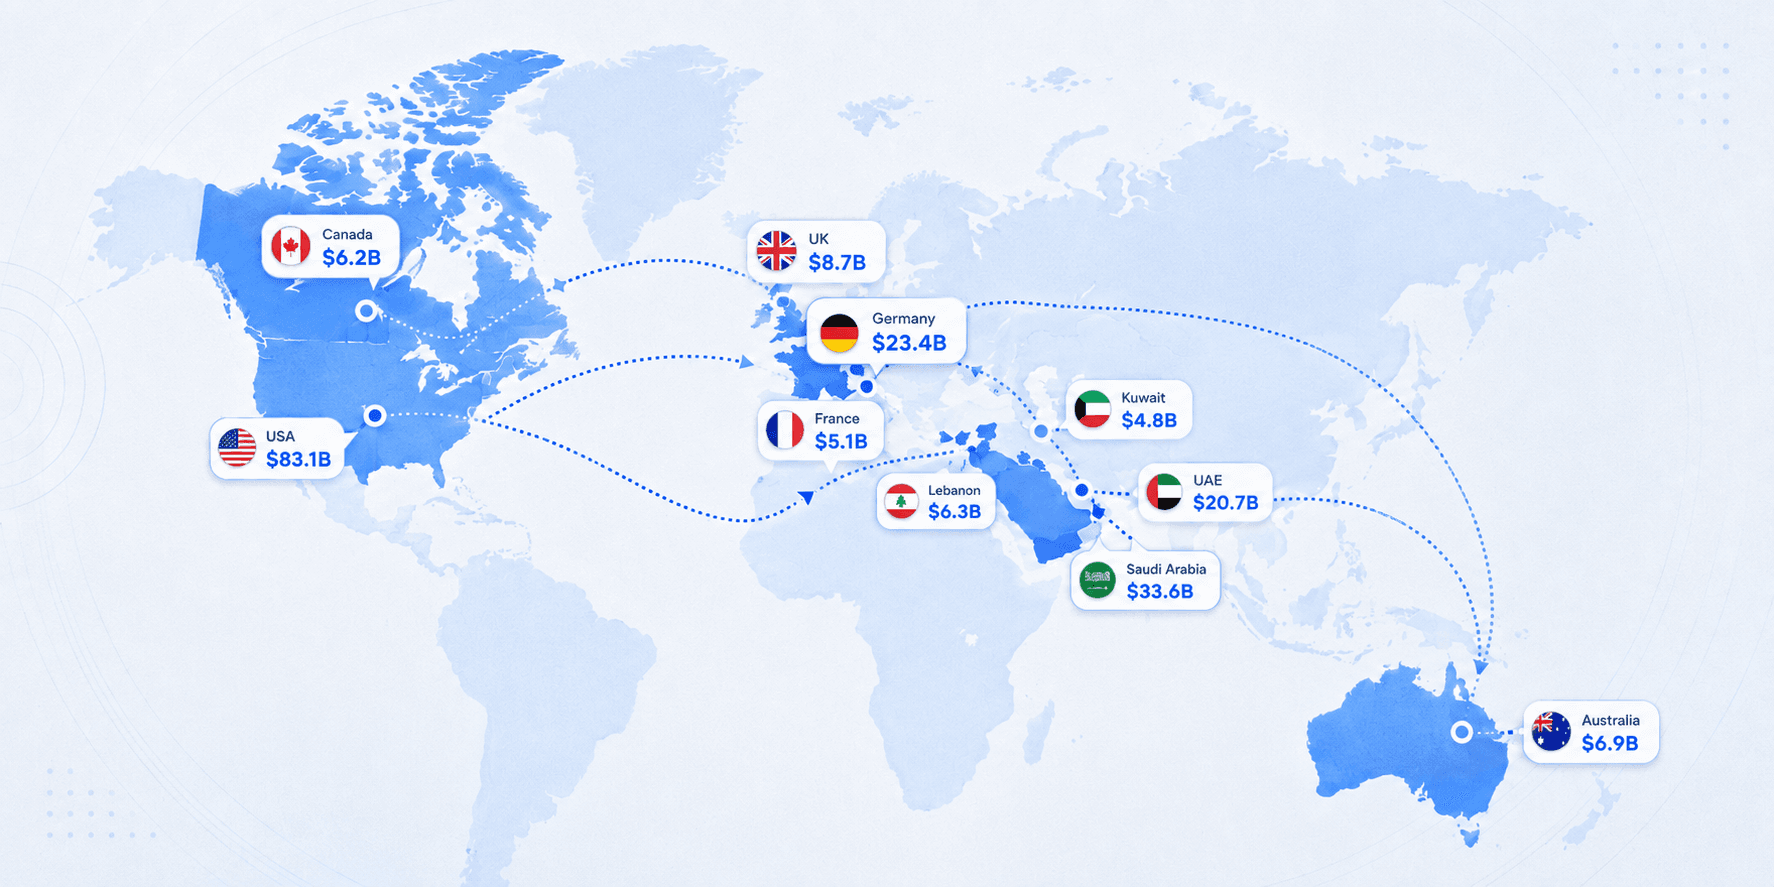
For international bank collections, Multi-Currency Accounts provide tracking, invoice matching, settlement visibility, and FIRA for supported inward remittances across 130+ global currencies from 180+ countries, with INR settlement to the merchant's Indian bank account.